Deutsche Bank Predicts 50% Copper Rally to $22,050 as Global Supply Squeeze Looms
As global stockpiling accelerates and greenfield mine developments lag, major financial institutions clash over whether copper is headed for an unprecedented physical liquidity squeeze or a macro-driven surplus.
 Editorial Team (ET)September 29, 2026
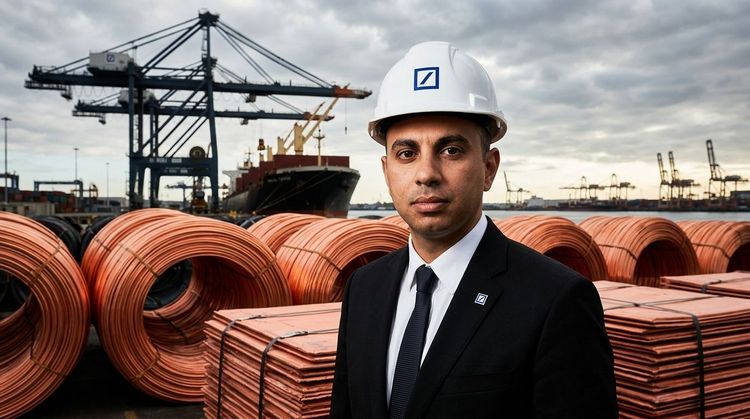
If you thought the global race for advanced microchips was intense, try running the modern economy without the metal that powers it all.
Deutsche Bank (ETR: DBK) has delivered a jolt to raw material markets, forecasting that copper prices could rocket 50% to an eye-watering $22,050 per metric ton by the second quarter of 2027.
Rather than a routine cyclical demand bump, Senior Metals Analyst Daniel Ghali frames the coming crunch as a full-blown physical supply liquidity crisis. Driven by a relentless strategic scramble, the United States and China are aggressive buyers in the physical spot market. According to Deutsche Bank estimates, accelerated national stockpiling could result in those two nations controlling roughly 71% of global copper supplies by the end of the year, leaving the rest of the world competing for a dwindling pool of available metal.
The underlying drivers feeding this market dynamic are as persistent as they are capital-intensive. AI-driven data center expansion, electric vehicle production, power grid modernizations, and renewable energy installations continue to demand vast quantities of conductor metal. However, mine supply operates on a completely different timeline. Developing a new greenfield copper mine from initial exploration to commercial production routinely takes 15 to 18 years. With mine outages and force majeure events hitting key operations in recent years, the global buffer has eroded to historic lows.
Deutsche Bank does not view a price spike as an isolated, temporary event. The bank projects average copper prices of $20,900 per metric ton across 2027, before settling at an average floor of $18,500 per metric ton in 2028. In Ghali’s analysis, available exchange inventories could drop toward zero unless prices climb high enough to ration demand or force industrial manufacturers toward lower-cost substitutes.