
The $22 Billion Feedgas Play: Shell Inks Megadeal for ARC Resources’ Decades of Natural Gas Inventory
How a $22 billion CAD megadeal secures Montney shale dominance for Shell plc (LSE: SHEL) and ignites a wave of consolidation across Canada’s junior energy market.
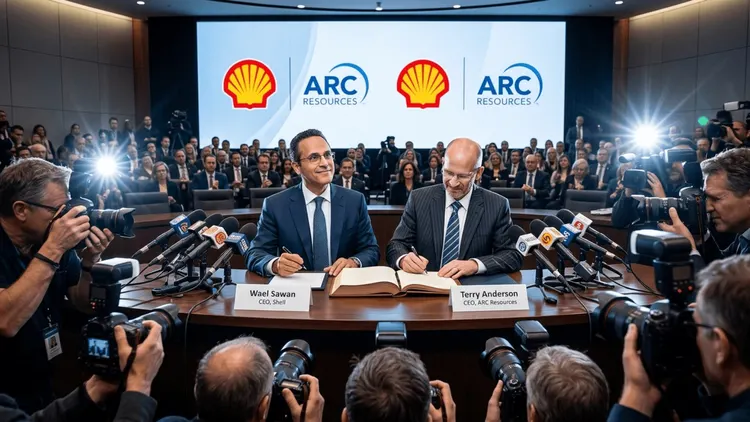
The Canadian energy patch just experienced the equivalent of a tectonic shift. On a seemingly ordinary April morning, global energy titan Shell plc (LSE: SHEL) announced it was swallowing up top-tier producer ARC Resources Ltd. (TSX: ARX) in a mammoth transaction valuing the enterprise at CAD $22 billion, or roughly US$16.4 billion. If anyone was wondering whether international supermajors had lost their appetite for Canadian rock, this definitive agreement serves as a roaring, multi-billion-dollar "no."
To understand the sheer gravity of the deal, you have to look at the math and the messaging. Shell plc (LSE: SHEL) is paying CAD $32.80 per share, which represents a massive 27 per cent premium to the target's last closing price on the Toronto Stock Exchange, or a 20 per cent premium over the 30-day volume-weighted average. The payout is structured as approximately 25 per cent cash and 75 per cent stock, meaning ARC shareholders get a quick payday while retaining long-term, dividend-paying exposure to a global powerhouse.
The leadership in Calgary clearly sees this as a crowning achievement. Terry Anderson, President and Chief Executive Officer of ARC Resources Ltd. (TSX: ARX), summarized the milestone perfectly: “Over our 30-year history, we have built a strong and resilient Canadian energy company defined by the depth of our world-class Montney assets, low-cost operations, leadership in responsible development, and high-performance people and culture.” He noted that through this transaction, the company will realize tremendous value and become part of a dynamic global energy leader capable of delivering on Canada's exciting energy future. The deal is so tightly knit that the board has unanimously recommended it, baking in a hefty CAD $600 million termination fee just in case another suitor tries to crash the party.
For Shell, the immediate gratification comes in the form of 370,000 barrels of oil equivalent per day added straight to their production metrics, effectively supercharging their compound annual growth rate to 4 per cent through to the end of the decade. But this acquisition is about far more than just immediate cash flow; it is a geographic masterstroke. By combining ARC’s sprawling 1.5 million net acres with its own 440,000 net acres in the Montney formation, Shell plc (LSE: SHEL) is locking down decades of top-tier, low-carbon-intensity inventory. Crucially, ARC’s vast natural gas reserves slot perfectly into Shell’s overarching strategy for the LNG Canada liquefaction plant. It is a textbook vertical integration play: secure the feedgas, feed the coastal infrastructure, and ship it to a hungry global market.
When a supermajor clears the board of a heavy hitter like ARC Resources Ltd. (TSX: ARX), it inevitably triggers a domino effect downstream, particularly for the junior market. The mid-cap operators left behind suddenly face an urgent scramble for inventory. To remain competitive and replace depleting reserves, these mid-tier players are practically forced to hunt in the junior market, looking to snap up smaller companies sitting on highly contiguous acreage.
Furthermore, this megadeal sets a fresh, highly attractive benchmark price for the Montney and Deep Basin regions. By paying a premium for low-cost production, Shell plc (LSE: SHEL) has effectively forced a valuation rerating for every junior producer sitting on similar rock. Investors will inevitably re-evaluate these smaller outfits, potentially driving up stock prices as market speculation mounts over who might be the next lucrative buyout target.
Then there is the sheer volume of capital rotation to consider. The cash portion of the transaction means institutional and retail investors will soon have a mountain of dry powder at their disposal. Historically, the energy sector is a highly insular ecosystem where investors tend to recycle buyout cash directly back into the junior and mid-cap spaces. This will inject a wave of much-needed liquidity into smaller companies hungry to fund their aggressive drilling programs or regional acquisitions.
Finally, the market should brace for a wave of asset spin-offs. Megadeals almost always result in an eventual shedding of non-core assets. Properties that are simply too small to move the needle for a behemoth like Shell plc (LSE: SHEL) often represent pure gold for an ambitious junior operator. Over the coming years, expect to see the supermajor divest these peripheral assets to pay down the debt assumed in the deal, creating prime acquisition opportunities for the next generation of Canadian energy producers.
In the end, this transaction proves that world-class rock paired with global infrastructure remains the ultimate trump card in the energy sector. Canada is now firmly established as a heartland for Shell's global portfolio, and the ripple effects will be keeping energy executives and junior market investors busy for years to come.
Sources:
- Shell plc Press Release: "Shell announces agreement to acquire Canadian energy company, ARC Resources Ltd (“ARC”)." (April 27, 2026).
- ARC Resources Ltd. Press Release: "ARC RESOURCES LTD. ANNOUNCES AGREEMENT TO BE ACQUIRED BY SHELL PLC" (April 27, 2026).