SPONSORED

Splitting a $40 Trillion Tab on Venmo: The Fiscal Absurdity Driving Peter Schiff’s Gold and Silver Forecasts

As the U.S. national debt marches toward $40 trillion, Wall Street and global central banks are quietly aligning with a mathematical reality that points straight toward a hard-asset revaluation.
•• 1 Min
Splitting a $40 Trillion Tab on Venmo: The Fiscal Absurdity Driving Peter Schiff’s Gold and Silver Forecasts

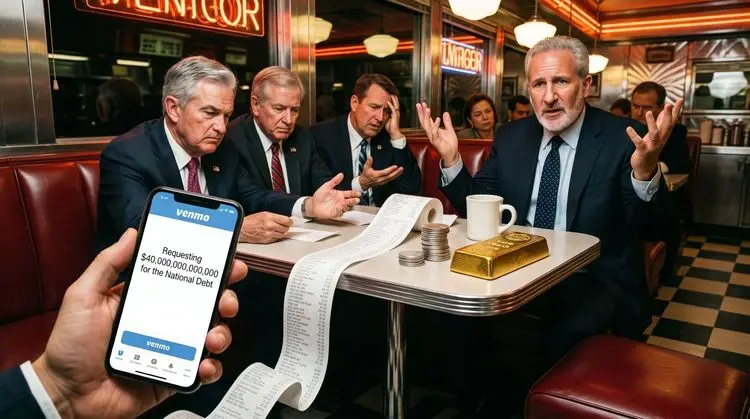
Imagine using the exact same mobile app you use to split a taco bill with your friends to chip away at a staggering $40 trillion national debt.

It sounds like a satirical punchline, but it is a verifiable reality on the U.S. Treasury Department’s Pay.gov portal. Under a program titled "Gifts to Reduce the Public Debt," patriotic citizens can now officially transfer their digital pocket change to Uncle Sam via Venmo and PayPal.

The math behind this digital tip jar, however, is beautifully tragic.

Since 1996, well-meaning Americans have chipped in a collective total of roughly $67.3 million, an amount that funds the federal government's current spending habits for a grand total of about 20 minutes. In fact, because the debt expanding at a dizzying pace, a citizen would have to submit Venmo's maximum possible transaction limit of $999,999.99 every 18 seconds just to keep up with the growth.

This crowdsourced band-aid is the ultimate mascot for the exact fiscal absurdity Peter Schiff has been warning against for decades.

In a recent appearance on MINING.COM’s Top of Mine interview series, the prominent economist and chief global strategist laid out an unapologetically bold roadmap that sees gold hitting $10,000 an ounce and silver skyrocketing to $200. While critics have long dismissed Schiff as a perpetual dollar bear, the current state of macroeconomics suggests the mathematical walls are closing in on the Federal Reserve. The immediate catalyst for the latest precious metals surge was a dismal June payrolls report, which recorded a meager gain of 57,000 jobs against the 100,000 economists expected. The numbers pushed gold back above the $4,100 per ounce mark as Wall Street wagered that a slowing economy would force the central bank to freeze interest rates in place. According to Schiff, however, retail investors are staring at the wrong scoreboard. The real crisis is an inescapable mountain of public debt, combined with annual deficits approaching $3 trillion and annualized interest expenses hurtling toward $2 trillion. In Schiff's estimation, the central bank has essentially run out of runway, entirely unable to restore price stability without triggering a systemic financial crisis.

While it is easy to paint Schiff as a lone contrarian, the institutional herd is quietly shuffling into the very same corner. Asset management heavyweights like Sprott Inc. (NYSE: SII) have pointed out the exact same fiscal cliff, noting that U.S. public debt has crossed a critical threshold where economic growth can no longer keep pace with net interest expenses. If the Fed keeps rates high to fight sticky, structural inflation, it risks breaking the banking sector and making the government's debt servicing completely unaffordable. If it cuts rates, inflation roars back. As institutional fund managers increasingly admit, the options are narrowing, and a return to hard money is becoming an inevitability.

Mainstream Wall Street isn't shouting $10,000 gold from the rooftops just yet, but their models are turning remarkably aggressive. Macro analysts at JPMorgan Chase & Co. (NYSE: JPM) are eyeing a push toward $6,000 by the end of the year, citing structural inflation, geopolitical fragmentation, and a powerful technical breakout. Meanwhile, commodity desks at Goldman Sachs (NYSE: GS) and Bank of America Corporation (NYSE: BAC) are continuously upgrading their long-term precious metals forecasts to account for an unprecedented wave of central bank accumulation and a distinct lack of alternative safe havens.

The global migration away from paper assets is no longer a mere hypothesis; it is a matter of public ledger. Nations are aggressively rotating out of Western debt, highlighted by Turkey's quiet liquidation of an estimated 85% to 90% of its U.S. Treasury holdings. Instead of sovereign bonds, capital is sloshing into the London over-the-counter market and Swiss refineries, where massive, opaque gold purchases by central banks, heavily driven by China and alternative sovereign wealth funds, are actively redefining global reserves and reversing the post-1971 fiat experiment.

This brings us to silver, where the narrative shifts from purely monetary defense to an aggressive industrial squeeze. While Schiff targets a staggering $200 an ounce, independent commodity analysts view a march toward $100 as the immediate structural milestone. Silver is currently riding a powerful dual-engine. Massive green energy infrastructure, global solar expansions, and AI-driven electrical grid upgrades are consuming physical silver at a pace mining supplies simply cannot match. When you layer that structural physical deficit on top of a classic gold-to-silver ratio compression, the white metal is primed to outpace its yellow sibling on a percentage basis.

This structural shift has created a massive valuation disconnect in the equities market. Traditional Wall Street analysts continue to price major mining firms under the assumption that elevated gold and silver prices are a temporary, cyclical anomaly. Because these analysts fail to grasp the underlying fiscal drivers pushing metals higher, they assume current mining margins are unsustainable.

Once the broader investment community wakes up to the reality that these elevated prices are the new baseline, a sweeping revaluation of the entire sector is expected. Institutional giants like Newmont Corporation (NYSE: NEM), Barrick Gold Corporation (NYSE: B), and Pan American Silver Corp. (NYSE: PAAS) stand perfectly positioned for a sweeping institutional revaluation. Schiff’s own asset management outfit, Euro Pacific Asset Management, has long maintained a strategy favored toward international, dividend-paying equities designed to withstand this exact type of dollar erosion. The longer the monetary can is kicked down the road, the more severe the ultimate fiscal reckoning will be when the road finally ends.

Sources

Core interview details and data matched from MINING.COM, "Schiff: ‘Trapped’ Fed sets up $200 silver, $10,000 gold," published July 8, 2026. Institutional context and market forecasts adapted from global research data provided by Sprott Inc. (NYSE: SII), JPMorgan Chase & Co. (NYSE: JPM), The Goldman Sachs Group, Inc. (NYSE: GS), and Bank of America Corporation (NYSE: BAC). Venmo donation metrics and debt tracking data provided by the U.S. Department of the Treasury Bureau of the Fiscal Service via Pay.gov and report analyses by Axios and Fox Business.

Most Popular News

  1. Cenovus Energy Acquires Athabasca Oil in C$5.7 Billion Mega-Deal
  2. Why Gautam Lohia Shifted from Global Consulting to Reboot a $20M Tech Micro-Cap
  3. Can Navy SEAL Leadership and Big Tech Scale Revolutionize Airborne Threat Detection?
  4. SpaceX’s $8B Spectrum Deal Sends AT&T, Verizon, and T-Mobile Plummeting
  5. Mark Carney Single-Outs NexGen's Rook 1 as a Critical Project of National Interest

Disclaimer


This report should not be viewed as investment advice or as an offer to buy or sell any securities or as an invitation or solicitation of an offer to buy or sell any securities. Neither the author of this report, its publisher, nor any other person associated with the publication of this report, are registered brokers, investment dealers, investment advisers, or financial advisers. The information in this report has not been tailored to the particular needs or circumstances of readers and should not be relied upon as investment advice or recommendations to purchase or sell any of the securities presented in this report. Readers seeking investment advice should contact qualified and registered brokers, investment dealers, investment advisers, or financial advisers prior to making any decision to buy or sell any of the securities referred to in this report. The information in this report should not be construed as investment, legal, or tax advice. No recommendation is made as to whether an investment in the presented securities is suitable for any reader in light of the reader’s particular circumstances.

Readers are cautioned that the publisher of this report covers exclusively securities that carry a high degree of volatility. Investing in such securities is highly speculative and carries a high degree of risk. Investors in such securities could lose all or a substantial portion of their investment. Only those investors who can afford to lose all or a substantial portion of their investment should consider investing in the securities referred to in this report.

This report may include information obtained from publicly available sources, including third-party reports or analysis. Neither the author nor publisher of this report, nor www.juniorstocks.com or its owners, have undertaken any independent investigation into the factual information used in this report, and the information in this report is provided without any warranty of any kind. No representations or warranties are provided regarding the accuracy or completeness of the information provided in this report. Statements of opinion or belief are those of the authors and/or publisher of this report. These statements of opinion or belief are expressions of the author’s and/or publisher’s judgment, and there is no guarantee that those judgments will turn out to be correct. No inference should be drawn that the author and/or publisher have any special or greater knowledge about the presented companies or their securities, or any particular expertise in the industries or markets in which the company operates. Readers should conduct their own due diligence and seek professional advice prior to investing in any securities presented on Juniorstocks.com.

Certain statements in this report constitute “forward-looking” statements. Forward-looking statements often, but not always, are identified by the use of words such as “seek,” “anticipate,” “believe,” “plan,” “estimate,” “expect,” “targeting,” and “intend” and statements that an event or result “may,” “will,” “should,” “could,” or “might” occur or be achieved and other similar expressions. Forward-looking statements express or involve discussions with respect to predictions, expectations, beliefs, plans, projections, objectives, goals, assumptions, or future events or performance; they are not statements of historical facts and should not be viewed as any guarantee of any future result. Forward-looking statements are based on expectations, estimates, and projections at the time the statements are made that involve a number of risks and uncertainties which could cause actual results or events to differ materially from those presently anticipated. The author and/or publisher of this report disclaims any obligation to update the forward-looking statements in this report, whether as a result of new information, future events, or results or otherwise. There is no assurance that forward-looking statements will prove to be accurate, as actual results and future events could differ materially from those anticipated in such statements. Accordingly, readers should not place undue reliance on forward-looking statements.

The information provided in this report is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to applicable law or regulation, or would subject the author or publisher of this report to any registration requirement in such jurisdiction or country.

Information about the editor of this publication:
Juniorstocks.com is a service provided by Piccadilly Capital Group, Office 66, 101 Clapham High Street, London, SW4 7TB, UK. Piccadilly Capital Group is not the publisher of this report and was not paid for the publication of this report. Piccadilly Capital Group seeks to generate web traffic and a growing number of followers through the publication of articles or reports. Directors, officers, and other insiders of the publisher own an interest in Piccadilly Capital Group. Piccadilly Capital Group does not endorse or recommend the business, products, services, or securities of any company mentioned on www.juniorstocks.com. Piccadilly Capital Group will not share your information with any outside third parties. Due to the new data protection basic regulation, we ask you to read our data protection declaration carefully.

Note on copyright:
The contents published on this website and on connected media (e.g., e-mail, X, Facebook) are subject to applicable copyright and ancillary copyright laws. Any use not permitted by applicable copyright and ancillary copyright laws requires the prior written consent of the provider or the respective rights holder. In particular, this applies to the duplication, editing, translation, storage, processing, or reproduction of content in databases or other electronic media and systems. Contents and rights of third parties are marked as such. Unauthorized reproduction or transmission of individual contents or complete pages is not permitted and is punishable by law. Only the production of copies and downloads for personal, private, and non-commercial use is permitted. Links to the provider's website are always welcome and do not require the consent of the provider of the website. Photos and images on the website may not be shared unless the publisher itself has acquired the initial rights from authorized sources. The presentation of this website in external frames is only allowed with written permission. If you notice any violations, please inform us. Please note: The content of our articles, emails, or other publications or social networks such as X, LinkedIn or Facebook is exclusively intended for the designated addressee(s). If you are not the addressee of these articles, emails, or other publications in the market letter or social networks such as Twitter or Facebook or his or her legal representative, please note that any form of publication, reproduction, or distribution of the content of these articles, emails, or other publications in the market letter or social networks such as X, LinkedIn or Facebook is prohibited. Falsifications of the original content of this message during data transmission cannot be excluded in principle.