The FED has a 3 bn dollar problem
Last year´s action leave very little space for the US central bank to act on future crises.
 Scott Wright (SW)October 5, 2026
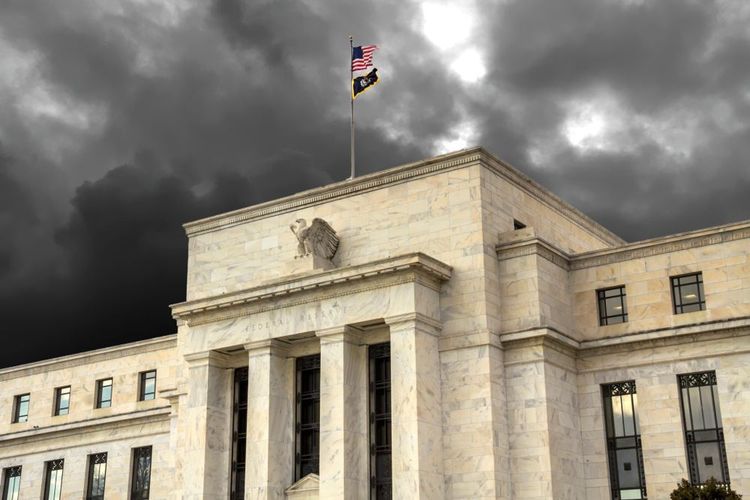
On Wednesday, the Federal Reserve announced plans to begin selling corporate bonds under the Secondary Market Corporate Credit Facility ("SMCCF"), an emergency credit facility that helped support credit markets during the pandemic. With this move, the central bank completes the move away from the market support programs it launched last year as part of a Covid-19 bailout program. Five of these emergency facilities expired at the end of 2020. The Fed says that as corporate bond spreads widen, the SMCCF portfolio sales will be gradual and orderly, aiming to minimize the potential for negative effects on bond markets, including daily liquidity and trading conditions for ETFs and corporate bonds. Corporate bonds seem to have taken the news well, with the largest credit ETF, iShares iBoxx $ Investment Grade Corporate Bond ETF (NYSEARCA: LQD), down slightly. Refinitiv Lipper's weekly report on fund flows in the US, which ended June 2, 2021, shows LQD had outflows of $ 605 million that week. LQD has $ 40.4 billion in assets under management (AUM). That is perhaps to be expected given that the Fed's move to unwind its corporate bond portfolio is relatively small compared to any future quantitative easing (QE) measures it might envision in the future. According to the latest central bank report, the Fed owned $ 13.8 billion in bonds and exchange traded bonds, a tiny percentage of the total corporate bond market of more than $ 10 trillion, according to the Securities Industry and Financial Markets Association. The Fed's holdings account for between 0.5% and 7.2% of the market capitalization of each fund.